Professional-authored detailed project reports for promoters, boards and CFOs committing ₹5 crore and above, prepared by named senior advisors — former bankers, sector economists and corporate finance specialists. Practising since 2010. Every DPR is written to the evidentiary standard of the institution receiving it, quoted as a fixed fee in writing, and delivered on the committed date.
Engagement dossierConsultancy
Engagement
Professional-authored DPR
Authored by
Four named senior advisors — assurance, credit, corporate finance, incentives
Scope
Proposals of ₹5 crore and above
Fee
₹55,999 – ₹8,60,000 · fixed, quoted in writing
Delivery
Usually 10–25 days · date committed
Appraised by
490+ institutions
2010
Practising since
490+
Institutions appraise Projectzo DPRs
142
Professionals team
22
Countries · 4 offices
01What the deliverable contains
What a DPR consultant delivers.
Twelve modules, named in the vocabulary a credit committee uses internally. A DPR consultant who cannot name them is describing a pre-built document, not a DPR.
01
Promoter, group & management profile
Group net worth, related-party exposures, existing borrowings and the credit history a committee cross-checks before it reads a single projection.
02
Cost of project & block capital
Land, civil works, plant and machinery, IDC, pre-operative expenses and a cost-overrun buffer — itemised against quotations an LIE can verify.
03
Means of finance & debt structure
Promoter equity, quasi-equity, consortium term debt and incentives, phased to implementation and held inside the lender’s gearing covenant, with DSRA sized.
04
Working capital assessment & CMA data (Forms I–VI)
Operating cycle, drawing power and MPBF under Tandon Method II for consortium limits.
05
Projected P&L, balance sheet, cash flow
Up to 25 operating years, built on capacity utilisation, input-output ratios and sector benchmarks.
06
Leverage, coverage & liquidity ratios
Debt-equity, TOL/TNW, interest coverage, FACR, security cover, net debt/EBITDA, DSCR and ISCR — each held to covenant — with current ratio, acid-test ratio and cash conversion cycle alongside.
07
Site, infrastructure & market feasibility
Site and infrastructure analysis, plant layout and engineering drawings, process design; market feasibility drawn from paid subscription databases and cited in-document — the pages a TEV reviewer reads first.
08
Profitability & returns
EBITDA margin, ROCE, RONW, operating leverage and break-even, with the margin of safety by year.
09
Investment appraisal
WACC-discounted NPV, project IRR, equity IRR, MIRR, discounted payback and profitability index — the metrics larger exposures and investors expect.
10
Sensitivity, tornado & scenario weighting
Volume, price and input-cost shocks of 5–15%; coverage ratios recomputed for every case; probability-weighted base, downside and stress cases.
11
Incentives & IND-AS 20 treatment
State industrial-policy capital subsidy, PLI and interest subvention — the grant treatment stated in the notes and run consistently through depreciation and coverage.
12
Rating, TEV & LIE readiness
Structured so an external rating agency, a lender-appointed TEV consultant and a lender’s independent engineer validate the DPR rather than rebuild it.
02Consultancy specimen
Six pages from DPRs the practice has written.
Displayed for inspection; never offered as a download. Redacted where the client requires it — otherwise exactly as the DPR consultant submitted it to the institution. Three of the six are not financial pages — they prove a practice, not a spreadsheet.
EXHIBIT 01 · INSPECT
Corporate DPR preface — integrated smart township under a state partnership, framed for an investment committee rather than a single lender
EXHIBIT 02 · INSPECT
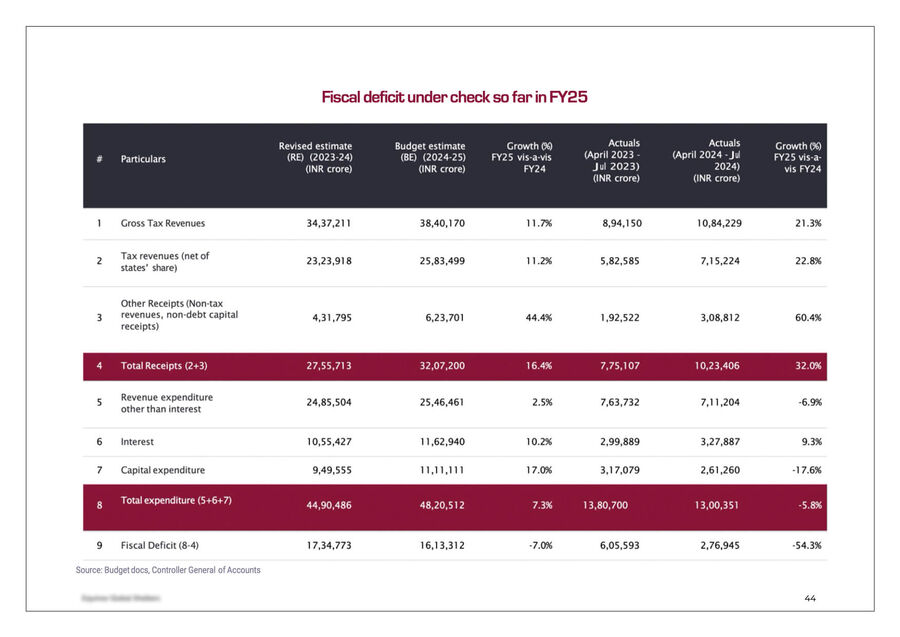
Macroeconomic context — Union fiscal position FY25, revised against budget estimates, sourced to the Budget documents and the Controller General of Accounts
EXHIBIT 03 · INSPECT
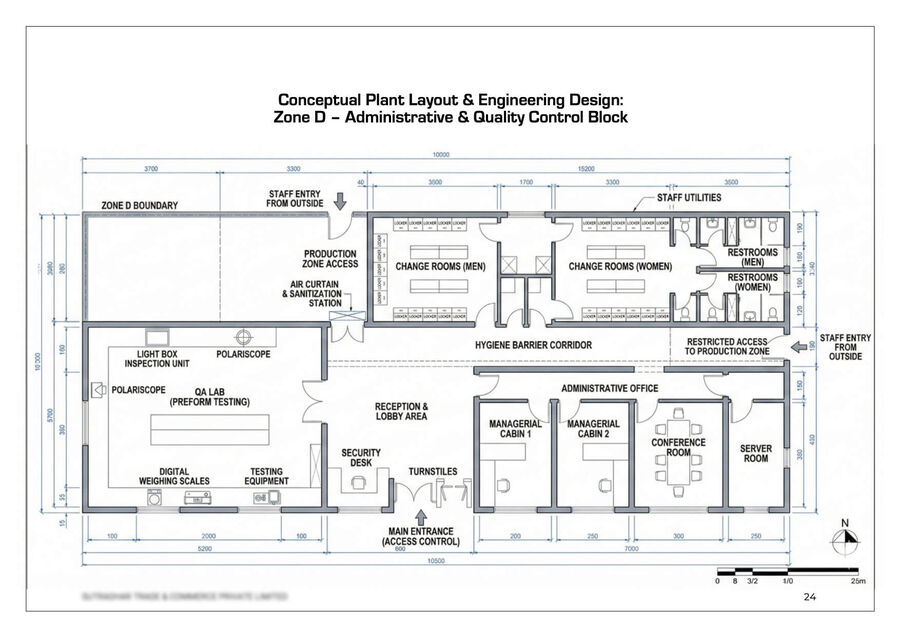
Zone D administrative and QC block — fully dimensioned: QA lab with polariscopes, hygiene-barrier corridor, turnstiled entrance, restricted production-zone access
EXHIBIT 04 · INSPECT
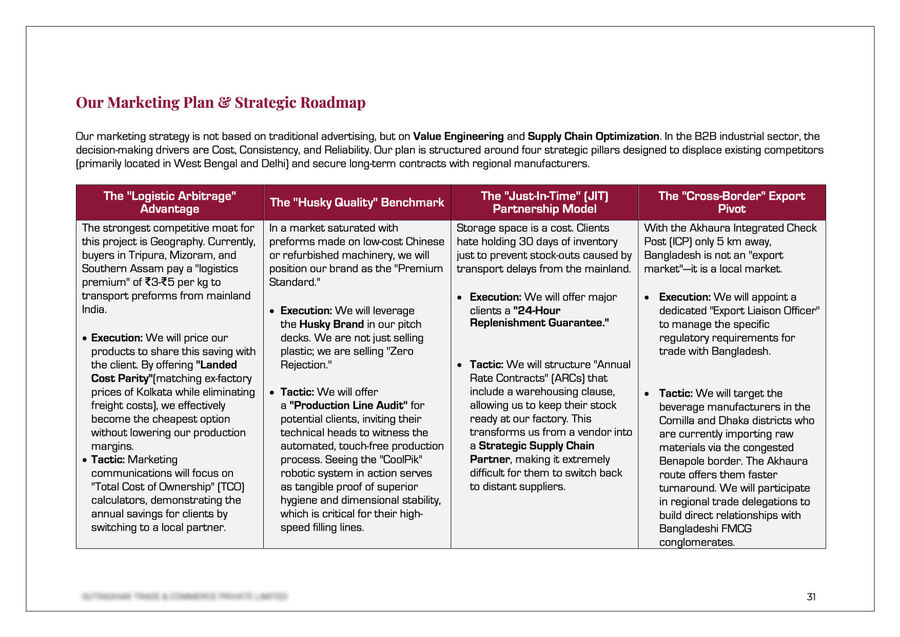
Go-to-market analysis — four pillars for a North-East preform unit: logistics arbitrage, quality benchmark, annual rate contracts, export via the Akhaura ICP
EXHIBIT 05 · INSPECT
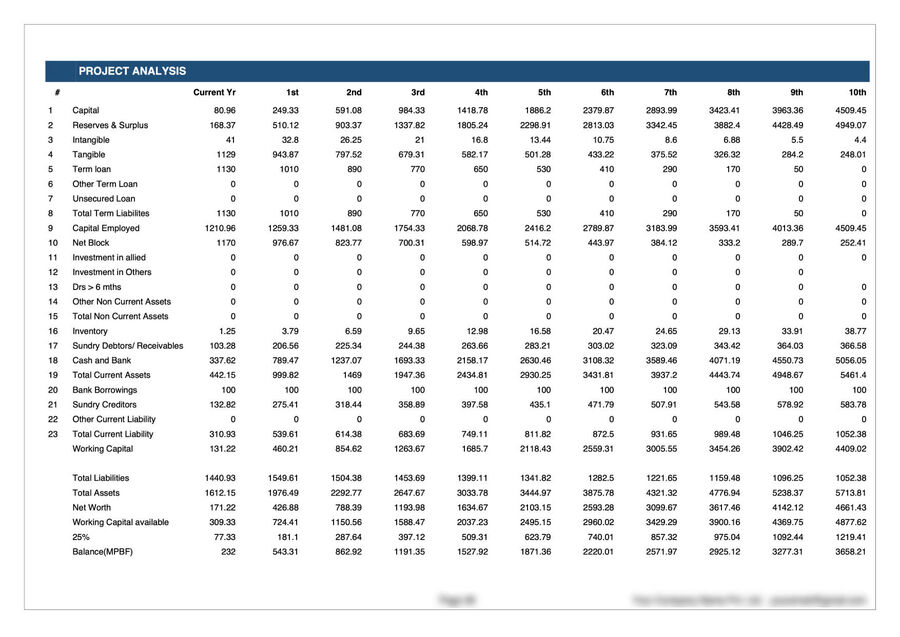
Project analysis — ten-year capital structure, net block, current assets and liabilities, net worth, and MPBF computed on the 25 per cent margin convention
EXHIBIT 06 · INSPECT
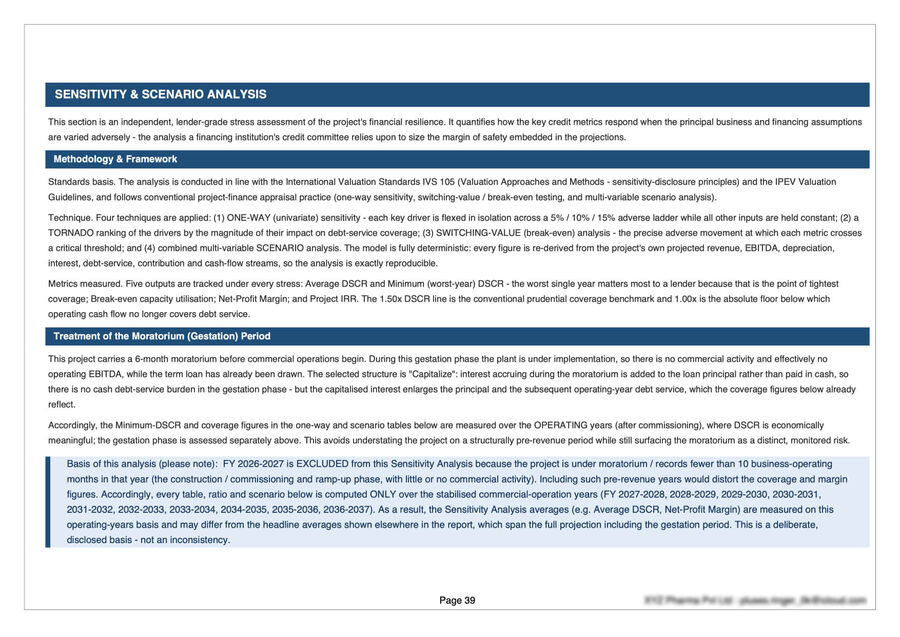
Sensitivity and scenario analysis — methodology under IVS 105 and IPEV: one-way ladders, tornado ranking, switching-value break-even, moratorium treatment of coverage
03Named authorship
The DPR consultant who holds the mandate.
No anonymous team. Each detailed project report is held by a named accountable partner and read adversarially by a second before it leaves the practice. The people below are accountable for it. Behind them sits the practice that produces it.
Signs off the financial statements in every DPR. Sixteen years across assurance, audit and institutional credit documentation — the standard a credit committee and a statutory auditor expect is the standard he prepares to.
Priya Iyer
Former Banker · Credit Appraisal
12 Years
Twelve years on the appraising side of the desk, deciding which term-loan proposals cleared the credit committee. Structures the coverage narrative and working-capital assessment in each DPR so the committee reads what it is trained to approve.
Anupam Saxena
Senior Financial Analyst · Projections
20 Years
Twenty years of corporate finance. Builds the projection model behind every DPR — up to 25 years of P&L, balance sheet and cash flow, with leverage, liquidity and return ratios covenant-tested before a single figure reaches the lender.
Niraj Khanna
MBA · Schemes & Government Liaison
Specialist
Maps each DPR to the incentive and instrument it qualifies for — PLI, state industrial-policy subsidies, SIDC land allotment, consortium structures — and prepares the compliance schedule the nodal agency and the lead bank will examine.
The practice behind them — seven disciplines produce each DPR
Research & market intelligenceData extraction from subscription databasesCivil & structural engineeringInfrastructure & plant layoutSector economistsDocument design & productionFinancial modelling
Market sections are drawn from paid subscription databases and cited in-document. Engineering drawings, structural decisions and utility matrices are produced in-house — the three-quarters of a Corporate DPR that precede the financials.
04Fit
Scoped to proposals of ₹5 crore and above. Stated plainly.
A DPR consultant who accepts every enquiry is not selective about the work. Projectzo is — and says so at the first conversation, so a proposal outside scope is not charged for a conversation it does not need.
Engaged for
+Proposals of ₹5 crore and above — term debt, working-capital consortia, or both
+CFO offices, boards and corporate finance advisers preparing institutional files
+Consortium and multiple-banking arrangements, external credit rating, TEV and LIE review
+PLI and state industrial-policy incentives; industrial land allotment through SIDCs
+Private equity, strategic investment and board-level documentation
+Promoters who need a named DPR consultant the credit committee can call
Not engaged for
−Proposals below ₹5 crore — the fee is disproportionate to the exposure
−Pre-built documents or fill-in-the-blank requirements
−Self-preparation support
−Two-day deadlines with no inputs ready
05Engagement scope and fees
DPR consultant fees. Three scopes, each stated before work begins.
The fee tracks the work a proposal needs — not its size. Every engagement is authored by the practice’s professionals; what changes across the scopes is how much site, engineering, market and structural work the proposal requires.
Standard
₹55,999
Promoter and group profile, cost of project and block capital, means of finance, CMA data in the six prescribed forms, full projections, ratio and sensitivity analysis — the complete DPR.
Fits
Single-unit proposals on a standard term-loan structure.
Professional
Quoted by scope
Everything in the Standard DPR, plus site and infrastructure analysis, plant layout and engineering drawings, manufacturing process design, market feasibility from subscription data and go-to-market analysis.
Everything in the Professional DPR, plus multi-unit modelling, consortium debt structuring, state incentive and IND-AS 20 treatment, land allotment documentation and investor-committee material.
Fee names the scope of the DPR, not the page count.
Worked example
A ₹6 crore single-unit expansion on a standard term-loan structure is a Standard engagement at ₹55,999. A greenfield unit of the same size needing site analysis, plant layout and market feasibility is a Professional engagement, quoted at the first conversation. Project size alone does not decide the fee — the work the proposal needs does.
Quoted in writing before any work on the DPR begins. No hourly billing.
✓
Revisions included
Queries raised by the institution on the DPR are answered within the engagement, not invoiced.
✓
Delivery date committed
The quotation states the exact delivery date.
06Process
Three stages. Each one dated.
Vagueness about timelines is how a DPR consultant signals inexperience to a promoter working to a sanction deadline. The quotation states the date.
STEP 01DAY 1–2
Consultation
A scoping conversation with the consultant who will author the DPR. An input checklist follows, then an official quotation stating the fixed fee and the exact delivery date.
STEP 02USUALLY 10–25 DAYS
Preparation
Modelling, covenant testing and instrument mapping by the assigned advisors; then a line-by-line adversarial read by the accountable partner before anything leaves the practice.
STEP 03THROUGH SANCTION
Delivery & support
A submission-ready DPR, followed by written responses to the institution’s queries and versioned re-issues — within the fee.
07Institutional appraisal
Appraised where the decision is made.
Consortium lead banks, NBFCs, rating agencies, state industrial development corporations and incentive boards — 490+ institutions have sanctioned on the strength of a Projectzo detailed project report. The cases below are drawn from the practice's engagement records: ticket size, sector, instrument, outcome.
Credit cases · anonymised · ₹5 crore and above
Ticket
Sector
Instrument
Outcome
Delivered
₹12.6 Cr
Pharmaceutical formulations · greenfield unit
Consortium term debt · working-capital limit · state capital subsidy
Sanctioned on first submission; no supplementary query from the credit committee
Day 20 of 21 quoted
₹12 Cr
Integrated cold chain
Consortium term debt
Sanctioned; lead-bank appraisal cleared
Day 14 of 15 quoted
₹38 Cr
Sponge iron & billet plant · brownfield expansion
Term debt · enhanced working-capital limit
Sanctioned; TEV study validated the DPR base case without rebuild
Day 24 of 25 quoted
₹7.4 Cr
Specialty chemicals
Term debt · state industrial-policy incentive
Sanctioned; incentive claim admitted on the DPR schedules
Day 12 of 14 quoted
₹64 Cr
Solvent extraction & edible-oil refinery
Consortium project finance
Sanctioned; external rating assigned on the DPR base case
Day 25 of 25 quoted
Promoters are not named and figures are rounded. Each record is held in the practice's engagement file with the sanction letter and the quotation that fixed the delivery date.
What the credit committee tests.
The DPR is built to the structure a credit committee is trained to read: leverage and coverage ratios computed to the lender's own covenants, incentives treated the way its policy prefers, and a sensitivity schedule that answers the committee's questions before they are asked.
Where a lender appoints an independent TEV consultant or an LIE, the DPR consultant prepares the detailed project report so the reviewer validates rather than rebuilds — which is what keeps a sanction on its original timeline.
08Scope reference
Scope of a DPR under the RBI Master Direction on Loans and Advances.
What a detailed project report must contain for an institution to appraise it, which schemes it serves, and where regulatory treatment applies.
Structure the institution expects
A DPR for a bank loan runs from promoter profile and feasibility to the financial core: cost of project, means of finance, projections and CMA data in the six prescribed forms. A competent DPR consultant writes each section for credit-committee scrutiny.
Covenants and the ratios behind them
On a bank loan of ₹5 crore and above, lenders test covenants: debt-equity of 2:1 to 3:1, DSCR averaging 1.50 (floor 1.25), TOL/TNW and current ratio within band, Tandon Method II for working capital. The DPR consultant stress-tests each against the lender's own covenant — see DSCR, MPBF and the current ratio and sensitivity analysis in a project report.
Scheme-specific treatment
Capital subsidies vary by state and project size, PLI tracks incremental production, and larger exposures draw TEV review. Grants under IND-AS 20 must run consistently through depreciation, DSCR and means of finance — the section most often rebuilt at the branch, and the one a detailed project report consultant gets right first.
09Coverage
DPR consultant across India.
Engagements are handled remotely by the same named DPR consultant; site visits are arranged where the institution or the project requires one.
Headquartered in Ahmedabad. Proposals from Indian promoters abroad, and from ventures in the USA, UAE and the Netherlands, are prepared by the same consultant to the standard of the institution the DPR will be submitted to.
10Questions a competent buyer asks
Before engaging a DPR consultant.
Each answer states its conclusion in the first sentence. Fourteen questions; all marked up for search.
Leverage and coverage first — debt-equity, TOL/TNW, interest coverage, fixed-asset coverage (FACR) and security cover — then debt service (DSCR and ISCR), then liquidity (current and acid-test ratios) and returns (ROCE, RONW). Most lenders hold DSCR to an average of 1.50 with a floor of 1.25 and debt-equity within 2:1 to 3:1, but the covenant set varies by lender and exposure. The practice’s DPR consultant computes each ratio to the lender’s own covenant, stresses it under adverse price and volume movements, and presents the sensitivity schedule in the DPR so the committee sees the cushion, not just the headline figure.
A named senior partner signs off the financial statements, and every DPR engagement carries an accountable partner whose name appears on the covering note. Where the institution requires certification by the promoter’s statutory auditor or a UDIN-backed attestation, the practice prepares the working papers to that standard and coordinates the sign-off.
Revisions arising from the institution's queries are included within the engagement. The consultant who authored the DPR handles the response — revised schedules, an updated CMA set, or a rebuilt sensitivity run — usually within two to four working days, and re-issues the document with a versioned covering note so the appraisal file stays clean.
Under IND-AS 20 a capital grant is either deducted from the cost of the related asset or recognised as deferred income and released over the asset's useful life. The practice follows the treatment the lending institution prefers, states it explicitly in the notes to the projections, and reflects it consistently in depreciation, DSCR and the means-of-finance schedule of the DPR.
A detailed project report is the complete proposal: promoter profile, technical and market assessment, cost of project, means of finance and projections. CMA data is the working-capital submission in the six prescribed forms and is normally one section of the DPR. A TEV study is an independent techno-economic viability opinion commissioned by the lender for larger exposures, often alongside a lender’s independent engineer — the DPR consultant prepares the detailed project report so a TEV reviewer can validate it without rework.
Usually 10 to 25 days from receipt of inputs, depending on project cost, instrument and the number of units. Every engagement begins with an official quotation stating the exact delivery date. Where a sanction deadline is fixed, it is raised at the first conversation and the DPR timeline is planned around it.
Term loans and working-capital limits from scheduled banks and NBFCs, including consortium and multiple-banking arrangements; project-finance structures with DSRA and security-cover covenants; external credit rating and lender-appointed TEV and LIE review; PLI incentives and state industrial-policy capital subsidies; industrial land allotment applications to state industrial development corporations; and DPRs supporting private equity or strategic investment. Each has its own appraisal logic, and the consultant structures the DPR to that logic.
Promoter profile and KYC, the project's location and land or building position, machinery and civil-works quotations, installed capacity and raw-material sourcing, the intended instrument or lender, existing borrowings and sanction letters, and — for an existing unit or group — the last three years of audited financials. The consultant reviews the inputs at the first conversation and confirms in writing what, if anything, is still needed before the DPR is drafted.
Every engagement is confidential by default. Documents are held on access-controlled infrastructure, shared only with the DPR consultant assigned to the file, and never reused as reference material for another client. A signed non-disclosure agreement is available on request before any material is exchanged.
Engagements range from ₹55,999 to ₹8,60,000, determined by project cost, the instrument applied for and the complexity of the financial structure. The fee is fixed and quoted in writing before work begins — there are no hourly charges and no additional cost for revisions the institution raises on the DPR.
Yes. A substantial share of the practice’s DPR work is commissioned by corporate finance advisory firms and CFO offices that need institutional-grade documentation without diverting their own partners. The DPR can be prepared for co-signature, and the engagement is handled with the firm as the client of record.
Not as consultancy engagements. Below that size the fee for human authorship is disproportionate to the exposure, and the proposal is better served by Projectzo’s software platform, which produces a sanction-ready DPR from the promoter’s inputs. Which route fits is said plainly at the first conversation.
Yes. A DPR prepared for an institution already carries the projections, unit economics and sensitivity work an investment committee expects. For private equity or strategic investors the document is extended with valuation support, scenario weighting and an investment-memorandum narrative, so one DPR engagement serves both audiences.
Because the people writing the DPR have sat on the approving side of the desk, the document is prepared to the standard 490+ institutions already appraise against, the fee is fixed in writing, and the delivery date is kept. Sixteen years of business consulting practice stand behind every DPR — and the consultant who writes it is named on this page.